
The primary residence is a fundamental concept in the areas of housing and taxation in Spain. It is not merely a place where we live; rather, its classification as such has significant implications in fiscal, legal, and social terms. In a country where housing tenure varies between ownership, rental, and squatting, it is essential to understand what constitutes a primary residence and how this affects citizens. In this article, we provide all the details on the subject. Let’s get started.


A primary residence is the property where a person actually and continuously resides. According to Spanish tax regulations, a primary residence is defined as the property that serves as the taxpayer’s permanent residence for an extended period.
For a property to qualify as a primary residence, it must be used as a stable residence and must meet certain conditions. Generally, the Tax Agency considers a home to be a primary residence if the owner or tenant resides there for at least 50% of the year. In other words, the amount of time a person spends in their home must be significant for that property to be considered their primary residence.
Identifying a home as a primary residence can affect your income tax return, as well as other aspects such as the Individual Income Tax (IRPF) and other property-related taxes.
For a residence to qualify as a primary residence and serve as the main home of its occupants, it must meet a series of requirements. First and foremost is the length of residence, which requires that the owner or tenant occupy the residence for more than 183 days a year. In addition, the primary residence must be the place where the residents’ vital interests are centered, such as work, their children’s education, and other fundamental aspects of their daily lives.
Although registration with the municipal census is not a formal requirement, this administrative act is considered a crucial indicator of habitual residence, as it reflects the individual’s connection to their residence. On the other hand, the layout and characteristics of the home are decisive; a primary residence is considered to be a space that allows for the conduct of daily life, whether it is a single-family home or an apartment in a building. Finally, it is essential that the property be registered in the name of individuals, since a residence cannot be considered a primary residence if it belongs to a legal entity, such as a corporation or partnership. These elements are not only fundamental to the classification of the residence but also ensure that the home fulfills its purpose as a family’s primary shelter.
Meeting legal and tax requirements is not enough if you cannot provide proof to the tax authorities in the event of an audit. To prove that a property is your primary residence, the first piece of evidence is your municipal registration, but it’s advisable to reinforce this with proof of continuous residence: utility bills in your name, employment contracts with employers located near the residence, or your children’s enrollment in schools in the area. It is also important to document the required period of occupancy—more than 183 days a year, though not necessarily consecutive—with documentation dated throughout that period. When the property includes annexes, such as a garage or storage unit acquired under the same deed, these are also considered part of the primary residence and must be listed in the property documentation. The more consistent these documents are, the stronger the taxpayer’s position will be in the event of an audit.
The main difference between a primary residence and a second home lies in their use and the duration of occupancy. A primary residence is the one where a person resides permanently and meets the requirements mentioned above. In contrast, a second home refers to a property that is not continuously or predominantly used as a primary residence but may be used occasionally for vacations, weekends, or specific seasons.
From a tax perspective, the distinction between these two types of residences is crucial. The primary residence is typically eligible for tax deductions and benefits, while a second home generally does not enjoy the same advantages and may even be subject to certain additional taxes.
Although they usually coincide, the tax residence and the primary residence are not exactly the same. The tax residence is the address the tax authority has on file as the point of contact for the taxpayer’s tax-related communications and procedures, whereas the primary residence is a specific category linked to particular tax benefits, such as the deductions or exemptions mentioned above. In practice, for individuals, both addresses should be the same, and in fact, it is the taxpayer’s responsibility to notify the Tax Agency of any change of residence to keep their tax address up to date. When there is a discrepancy between the two—for example, if someone moves but does not update their information—it can lead to confusion regarding official notifications and may even make it difficult to prove that a property is one’s primary residence in the event of a tax audit.
The Tax Agency has several mechanisms for determining whether a residence is considered a primary residence. These include:
The identification of your usual residence is based on a combination of information that the Tax Agency obtains from various sources. These include:
Taken together, all this information allows the tax authorities to build a fairly comprehensive profile of a taxpayer’s housing situation.
The primary method for declaring your primary residence is through Form 100 of the personal income tax return, which details the taxpayer’s financial situation. To correctly declare your primary residence, it is essential to identify the property by specifying its address and characteristics. In addition, it is important to accurately report all income earned and document any applicable deductions you may be eligible for as a result of owning a primary residence. The tax return can be filed online through the Tax Agency’s Electronic Portal or in person at designated offices. It is also essential to maintain supporting documentation that includes all documents proving both ownership and the status of the residence as your primary residence, as the Tax Authority may request this during a subsequent audit.
Your primary residence has significant tax implications; therefore, if this is the first time you are declaring your primary residence, it is advisable to seek the advice of an expert—such as a tax advisor or an attorney specializing in tax law—to ensure everything is in order and to avoid potential errors that could affect your tax situation.

In Spain, tax regulations offer tax benefits, exemptions, or reductions to individuals who use a property as their primary residence or habitual residence. Here are the key considerations to keep in mind:
Inclusion in the Personal Income Tax Return
It is mandatory to include the primary residence deduction in your personal income tax return (IRPF) in the corresponding proportion, even if you are not required to pay tax on it.
Mortgage Deduction
If you purchased the property before 2013, you can deduct 15% of the amounts used to pay the mortgage, up to a limit of 9,040 euros.
Deductions for Home Improvements
There are other deductions related to home improvements:
Beyond the deductions already mentioned, the regulations provide for other significant tax benefits related to the primary residence. The reinvestment exemption allows taxpayers to avoid paying tax on the profit obtained from the sale of their primary residence, provided that the proceeds are reinvested in the purchase of a new primary residence within two years following (or preceding) the sale; if the reinvestment is only partial, the exemption applies on a pro-rata basis. On the other hand, individuals over the age of 65 are entitled to a full exemption when selling their primary residence, with no obligation to reinvest the proceeds in any other property. In addition to these national benefits, there are regional tax credits—additional deductions that each autonomous community may establish within the regional portion of the personal income tax (IRPF)—for example, for young people, large families, or people with disabilities—which should be reviewed on a case-by-case basis, as they vary significantly from one region to another.
Additional Recommendations
A second home cannot be considered a primary residence in the strictest sense, since the concept of “primary residence” requires permanent residence at that location for an indefinite period. However, there are specific circumstances in which a second home can be designated as a primary residence. For example, if you decide to change your residence and move into your second home while meeting all the requirements for “habitual residence,” it could be officially recognized as your new primary residence. Likewise, situations related to work or personal activities can influence this classification; for example, if a job or a personal project requires you to stay at your second home for more than 183 days and you can prove this fact, in theory, it could be feasible for that property to be considered your primary residence. These situations illustrate how, under certain conditions, a second home can take on a new role and status in your daily life.
By regulation, a taxpayer may only have one primary residence. This concept is clearly established to prevent the abuse of tax benefits and deductions. Having more than one primary residence is not only fiscally unfeasible but can also lead to complications and legal problems.
However, it’s important to note that you can own multiple properties, but only one of them can be considered your primary residence—and that will depend on the length of your stay, your registration in the municipal census, and other factors we’ve already mentioned.
A home may cease to be considered a primary residence under certain circumstances that alter its use and place of residence. First, due to a change in residence, when the owner or tenant decides to move and establish their life elsewhere for more than 183 days a year; in this case, the original home loses its status as a primary residence. In addition, the vacancy of the property is another critical factor; if the home remains empty for an extended period with no intention of being occupied, it may also cease to be classified as a primary residence. Finally, the loss of characteristics that affect its functionality—such as if the home undergoes modifications that render it uninhabitable or if it becomes an investment property without personal use—directly influences its status as a primary residence. These aspects are fundamental in determining when a home no longer meets the requirements to be considered a person’s primary residence.
You can get started safely and profitably with Domoblock, the advanced blockchain-based investment platform developed and managed by experts to offer you unbeatable opportunities for profitable investments, backed by extensive experience in real estate tokenization and real estate crowdfunding. It’s real estate, and you can achieve your goals and secure your financial freedom for the future!
Start with as little as €200 and earn returns of over 10% in less than 8 months.
Start securing your financial future—and that of your entire family—with a reliable and transparent alternative on Domoblock!
The primary residence is a key element in the tax and personal lives of residents in Spain. Understanding its definition, requirements, and the correct way to report it is essential to avoid legal complications and maximize tax benefits. From the distinction between primary residences and second homes to how to file and claim deductions, every aspect is relevant to ensuring that tax rights and obligations are upheld. Proper management of your primary residence not only affects your tax situation but also has a significant impact on your personal and family well-being.
It is essential to stay up to date on any changes in the regulations, and when in doubt, it is always advisable to seek professional advice to ensure compliance with tax obligations and the proper use of the benefits allowed under Spanish law.

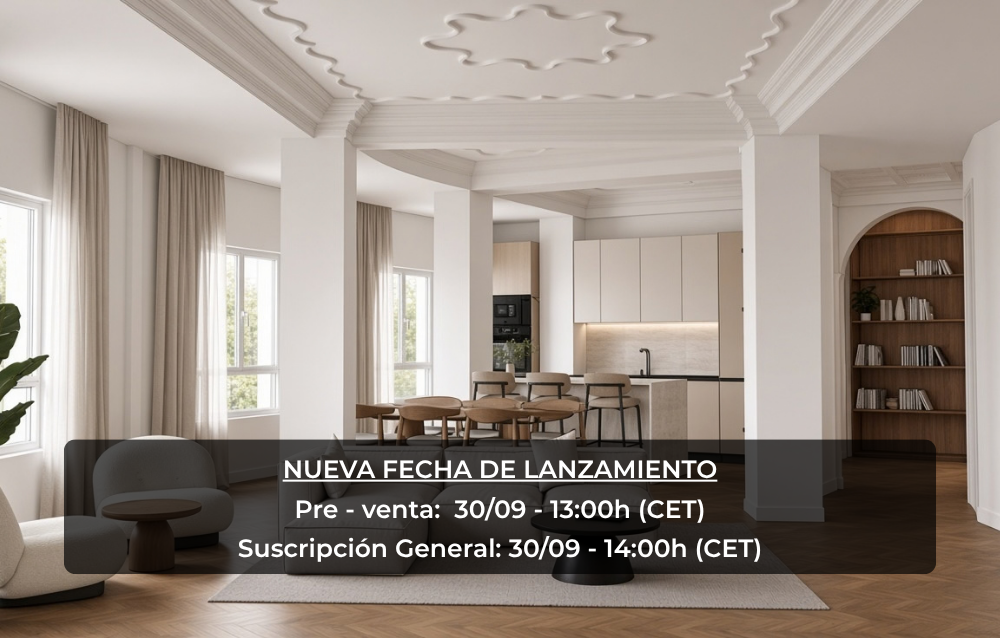

41 Av. del Oeste
Funded
100%
763.249,36 €
Target
€763,249.36