Paying off a loan or mortgage early is one of the most effective ways to reduce your debt. However, before taking this step, it’s a good idea to consider whether reducing your monthly payment or the loan term is right for you and whether there are any cost-effective alternatives.

Early repayment of a mortgage involves paying off part or all of the outstanding principal before the date agreed upon with the bank.
There are two main types of prepayment, depending on the scope of the payment.
You pay a certain amount to reduce the remaining debt, while keeping the term of the mortgage or loan the same.
You pay off the entire outstanding balance, thereby completely terminating the loan agreement.
When you make an early repayment, the financial institution applies that amount in an order governed by law and by the loan agreement itself.
The interest accrued from the last day of your monthly payment period until the exact date the extra payment is made is deducted.
If your contract includes an early repayment fee, the bank deducts this amount.
The remainder of the amount paid goes entirely toward paying down the outstanding balance.
When you make an early payment, the money goes directly toward reducing the outstanding principal, triggering a chain reaction that saves you money.
During the first few years of the mortgage, most of your monthly payment goes toward paying interest and very little toward reducing the principal.
By eliminating interest that would have accumulated and compounded over 10, 15, or 20 years, every dollar paid today saves you future interest.
When you make a partial payment, the bank allows you to choose between two options:
Your monthly payments are recalculated downward, while maintaining the original repayment term. This is useful if you need to reduce your fixed monthly expenses.
You keep the same monthly payment, but shorten the number of years or months of the loan. Mathematically, this option results in greater total savings on interest.
To calculate the exact figures for an early repayment, use the French amortization formula (the method used by virtually all banks).
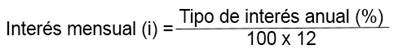

If you choose to reduce the payment (keep the remaining term “n” in months), calculate the value of the new monthly payment “m” using the standard payment formula:
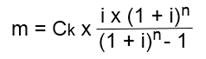
If you choose to shorten the term (keep the same monthly payment “m”), calculate the new number of remaining months “n” using logarithms:
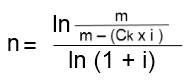
Early repayment fees are charges the bank may impose when you repay part or all of a loan before the term ends.
For fixed- or variable-rate mortgages, a prepayment penalty may only be charged if the prepayment results in a demonstrable financial loss for the bank.
For consumer loans, the limits are usually different from those for mortgages:
The fee amount can never exceed the total interest you would have paid had you not made the prepayment.
The main feature of prepayment on a fixed-rate mortgage is the stability of interest rates and the legal limits applicable to fees for cancellation or prepayment.
Since you have a fixed rate, the interest you pay on the principal does not fluctuate with the market (as is the case with the Euribor for variable-rate mortgages). This makes calculating the exact impact straightforward and predictable.
When you make an extra payment or pay off your fixed-rate mortgage in full, the bank may charge you an early repayment fee.
Early repayment on a variable-rate mortgage involves paying off principal ahead of schedule when your monthly payment and interest are tied to a benchmark rate—specifically, the Euribor mortgage rate plus a spread.
Unlike a fixed-rate mortgage, with a variable-rate mortgage, the impact on future savings will fluctuate every time your interest rate is adjusted.
When interest rates fall, fees may be temporarily suspended or eliminated. However, paying down principal when interest rates are high maximizes the financial return on your payment.
Paying off a loan or mortgage early (paying down principal ahead of schedule) is one of the most common financial decisions. This is due to the following advantages:
It reduces your leverage, which improves your credit profile with financial institutions for future transactions.
The main benefit. By reducing the outstanding principal, future interest is calculated on a lower amount, which lowers the total cost of the loan.
Eliminating or reducing debt provides a direct emotional benefit by lightening the burden of fixed monthly obligations.
Paying off too much principal without maintaining an adequate emergency fund (3 to 6 months’ worth of expenses) can leave you vulnerable to unforeseen events (unemployment, emergencies, repairs).
Depending on the contract and applicable law, the lender may charge a fee on the principal paid off.
Paying off a mortgage early is advisable when your financial circumstances and market conditions make reducing your debt more advantageous than keeping or investing that money.
Paying off your mortgage offers you a tax-free “guaranteed return” equivalent to your loan’s interest rate. If your mortgage is at 3.5%, paying it off is equivalent to investing with a guaranteed return of 3.5%.
During the first half of the loan term, the largest portion of your monthly payment goes toward interest. Paying down the principal early drastically reduces the remaining principal and maximizes your cumulative interest savings.
If you anticipate a future reduction in income or are seeking greater family stability, making extra payments to lower your monthly payment will give you more financial breathing room each month.
Although paying down a mortgage or loan eliminates debt and saves on interest, it isn’t always the most financially efficient decision.
If an unexpected expense arises and you don’t have cash on hand, you’ll have to resort to personal loans or credit cards with much higher interest rates (8%–20%).
If you took out a fixed-rate mortgage at historically low rates, it’s more beneficial to invest that capital in low-risk instruments that yield returns higher than the cost of your mortgage.
If your investment profile tolerates risk and you have a long-term horizon, historically, investing has outperformed the cost of an average mortgage.
The main difference lies in the amount of money you repay and whether the loan agreement remains active or is terminated.
Mathematically, shortening the term always saves more money on interest. However, financially and in practice, reducing the monthly payment offers greater flexibility and security in the face of unforeseen events.
Yes, you can make prepayments on a loan or mortgage as many times a year as you like. There is no legal requirement limiting you to a single annual payment.
If, after comparing both scenarios, you decide that making extra payments isn’t the best option for you, that capital can also work for you in another way.
With Domoblock, you can invest in real house-flipping projects in Spain starting at just €200, without having to manage a property or deal with the costs associated with an additional mortgage. The platform digitizes these assets through real estate tokenization, allowing you to access their potential appreciation easily and entirely online.
In addition, the entire process is backed by blockchain technology, which provides transparency and traceability for every transaction. Before any opportunity is published, a team of specialists analyzes its viability, thereby offering a real estate investment alternative free from the sector’s traditional barriers.
You can explore all our real estate investment projects in Madrid, Alicante, Zaragoza, and Valencia, Real Estate Investment in Altea, Real Estate Investment in Xativa, Real Estate Investment in Arganda del Rey, and Real Estate Investment in Moncofar.
Check them out!
The best decision isn’t the one that pays off your debt the fastest, but the one that provides you with the greatest long-term stability and returns. Before making an extra payment, make sure you don’t deplete your capital. Domoblock is with you every step of the way.


41 Av. del Oeste
Funded
100%
763.249,36 €
Target
€763,249.36